DSCR Investing in Meridian, Idaho: What Rental Investors Need to Know in 2026
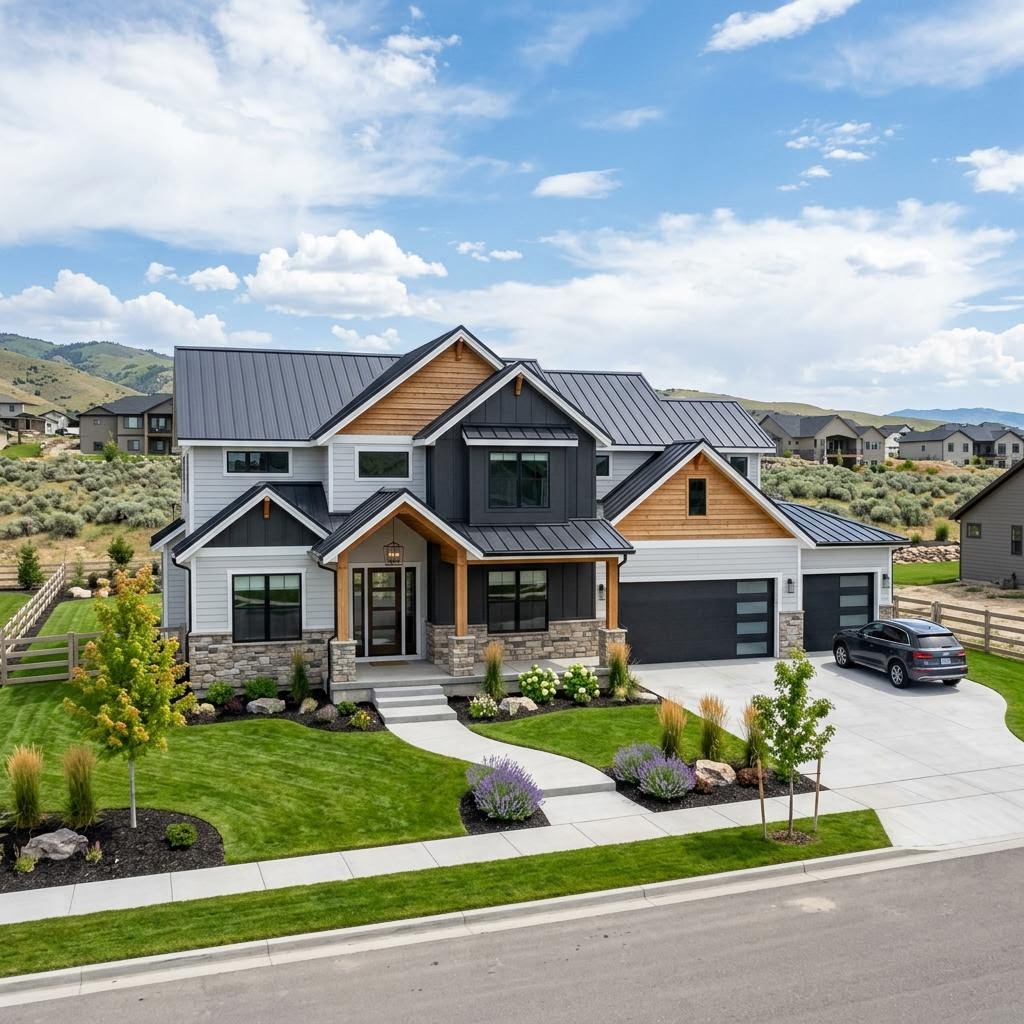
Meridian has attracted significant investor interest in recent years, but DSCR qualification is determined by qualifying rent, PITIA, and lender program on a specific property — not by a market's growth rate. The financing math still has to work on its own terms.
For investors evaluating a DSCR loan in Meridian, understanding how acquisition price, qualifying rent, appraisal methodology, and financing structure interact matters more than the market headline.
Why Growth Rate Matters for DSCR Investors
Standard DSCR programs generally qualify primarily from the property's rental income and property-level cash flow rather than a conventional personal debt-to-income calculation, while credit, assets, reserves, property type, leverage, guarantor requirements, and lender/program overlays may also apply.
Meridian's growth trajectory has brought employment centers, healthcare facilities, and commuter demand into the market — all of which support a rental tenant base. What drives DSCR qualification, though, is the qualifying rent on a specific property relative to its PITIA. Market growth is context; the property-level numbers are what qualify the loan.
One feature of Meridian's market that is directly relevant to DSCR investors: new-construction investment properties may be eligible for DSCR financing.
- New construction may be eligible for DSCR. For eligible vacant or new-construction investment properties, some lenders permit qualifying rent to be supported by an appraiser-established market rent schedule rather than an executed lease. Eligible properties, qualifying methodology, occupancy and lease requirements, and documentation standards vary by lender and program. See: Market rent vs. lease rent in DSCR underwriting.
Meridian's Investment Corridors
Ten Mile Crossing
A southwest Meridian growth corridor with an active new-build pipeline and nearby employment centers. Patrick regularly structures DSCR loans for new-construction purchases in this part of Meridian.
South Meridian
Established neighborhoods with long-term rental demand from Boise commuters and healthcare workers at St. Luke's Meridian. A mature submarket with a consistent demand profile.
Linder / McMillan Corridor
Mid-Meridian area with newer construction, strong school districts, and family rental demand from professional workers. Active new-build inventory in recent years.
Central Meridian
Downtown Meridian's Village mixed-use district has created demand for walkable rentals near retail and dining. A developing submarket with revitalization activity.
Southeast Meridian
Borders Boise's southwest side, putting this submarket within reach of both Meridian employment centers and downtown Boise. Proximity to BSU may extend the tenant pool for some properties.
New Construction DSCR Loans: How They Work in Meridian
For a new construction investment property, there's no existing lease to use for income documentation. For eligible vacant or new-construction investment properties, some DSCR programs permit qualifying rent to be supported by an appraiser-established market rent schedule. The appraiser develops a market rent conclusion based on comparable rental properties in the submarket, and that analysis may be used to support DSCR qualification — subject to lender program requirements.
Property eligibility, qualifying methodology, occupancy and lease requirements, and documentation standards are program-specific. Not every DSCR lender permits projected rent on a vacant property. See: How market rent and lease rent are treated differently in DSCR underwriting.
Patrick regularly structures Meridian DSCR loans for new-build purchases in Ten Mile Crossing and other growth corridors.
Sample Deal: New Construction Meridian
Purchase price: $550,000
Loan amount (20% down): $440,000
Monthly P&I at 7.25%: ~$3,003
Taxes + Insurance: ~$650/month
Total PITIA: ~$3,653
Appraised market rent: ~$3,700–$3,900/month
DSCR ratio: ~1.01–1.07
Illustrative example only — not a representation of current available rates, rents, loan terms, or typical Meridian property performance. Actual DSCR, payment, and qualifying rent depend on the specific property, program, rate environment, and lender requirements at time of application.
What Meridian Investors Should Model Before Buying New Construction
Meridian's growth creates investor interest — it doesn't guarantee the financing math. Before making an offer on a new-construction rental, investors should model:
- Purchase price vs. completed appraised value. Acquisition price and appraisal value don't always converge on new construction. See: How income and appraised value interact in DSCR financing.
- Qualifying rent methodology. Confirm with your lender whether the program permits appraiser-established market rent for a vacant property, and what the documentation requirements are.
- Realistic market rent. The appraiser's market rent conclusion is based on comparable rentals in the submarket at the time of appraisal. Model conservatively.
- Full PITIA. Principal, interest, taxes, insurance, and any applicable HOA. The sample deal above illustrates how thin the margin can be at these price points.
- Required reserves and liquidity. DSCR programs typically require reserve documentation after closing. See: DSCR reserve requirements.
- New-construction property eligibility. Program eligibility for vacant or pre-lease properties varies by lender. Confirm before committing.
- Intended refinance or exit strategy. If you plan to refinance after tenants are in place, model the expected DSCR at that point. See: How appraisal methodology affects refinance equity access.
Use the DSCR calculator to model your specific scenario. A Meridian DSCR lender can confirm program-specific eligibility and structure. See also: How to choose a DSCR lender in Idaho.
DSCR Loan Structure for Meridian Properties
Available down payment and leverage depend on the lender and program, DSCR ratio, credit profile, property type, loan size, and transaction structure. Requirements vary across programs — a DSCR lender can structure the specific parameters for a given Meridian property.
Many business-purpose DSCR programs permit eligible LLC vesting. Entity structure, guarantor requirements, and lender program eligibility rules vary by program.
Working with a Meridian-Based DSCR Lender
Patrick Penner is based in Meridian and has personally financed investment properties throughout Ada County and the Treasure Valley. He understands the local market firsthand — the Ten Mile Crossing new-build pipeline, how rents compare between South Meridian and the Linder corridor, and what appraisers are seeing in each submarket.
If you're evaluating a Meridian investment property, get a free quote and Patrick will structure the deal around the specific property's numbers. See also: Idaho DSCR loan programs and common reasons DSCR loans are denied.
Frequently Asked Questions
- Are DSCR loans available for Meridian investment properties?
- Yes. DSCR loans are a common financing structure for Meridian investment properties. Standard programs generally qualify based on the property's rental income and cash flow rather than a conventional personal income calculation, subject to credit, reserves, property type, leverage, and lender/program overlays.
- Can a new-construction rental in Meridian qualify for a DSCR loan without a tenant?
- Some DSCR programs permit qualifying on appraiser-established market rent for eligible vacant or new-construction investment properties, without requiring an executed lease at closing. Property eligibility, qualifying methodology, and documentation requirements vary by lender and program.
- How do lenders determine qualifying rent on a new Meridian rental?
- For eligible properties, qualifying rent may be supported by a market rent schedule from the appraisal rather than an executed lease. The methodology, eligible property types, and documentation standards are program-specific. Lenders that permit projected rent on vacant properties typically require an appraisal that includes a market rent analysis from a licensed appraiser.
- How much down payment is required for a Meridian DSCR loan?
- Required down payment depends on the lender and program, DSCR ratio, credit profile, property type, loan size, and transaction structure. Requirements vary across programs. A DSCR lender can structure the specific parameters for a given property and scenario.
- Does Meridian's population growth automatically improve DSCR qualification?
- Population growth can influence rental demand over time, but it does not determine DSCR qualification. Qualification depends on the specific property's qualifying rent, PITIA, loan amount, credit, and lender/program requirements. A property in a growing market can still fail to qualify if the acquisition price, financing terms, and qualifying rent don't produce an adequate ratio.
- Why can two Meridian properties with similar rents produce different DSCR ratios?
- DSCR is calculated as qualifying rent divided by PITIA. Two properties with similar gross rents can produce different ratios if acquisition prices, down payments, interest rates, loan amounts, taxes, insurance, or HOA costs differ. Qualifying rent methodology, property type, and lender program also affect the ratio. The purchase price and financing structure matter as much as the rent.
- Can a Meridian DSCR property close in an LLC?
- Many business-purpose DSCR programs permit eligible LLC vesting. Entity structure, guarantor requirements, and lender program eligibility rules vary. Confirming whether a specific entity and transaction structure is eligible is part of the loan structuring process.
- What should I calculate before buying a new-construction rental in Meridian?
- Model the full PITIA (principal, interest, taxes, insurance, and HOA if applicable), the qualifying rent methodology your lender will use, the resulting DSCR ratio, required down payment and reserves, and whether the completed property's appraised value supports the acquisition price. Meridian's growth creates investor interest — it does not guarantee the financing math. The numbers on the specific property have to work.
About the Author
Patrick Penner
NMLS #459913 • Coast2Coast Mortgage • Licensed in 46 States
Patrick Penner is a mortgage strategist specializing in DSCR and investment property financing, helping investors structure lending around rental income, portfolio growth, liquidity, and long-term strategy. Based in Idaho and working with investors nationwide, he focuses on helping clients navigate financing beyond traditional lending approaches.
His work includes DSCR purchases, refinances, cash-out strategies, BRRRR properties, Airbnb and short-term rentals, co-living, PadSplit, care homes, mixed-use properties, and other specialty investment scenarios.
Prefer our DSCR insights?